Analysis of the Nguyen Binh Khiem Building Sale, District 1: Investment Opportunity or Cashflow Challenge?
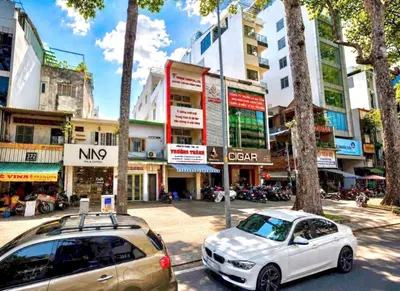
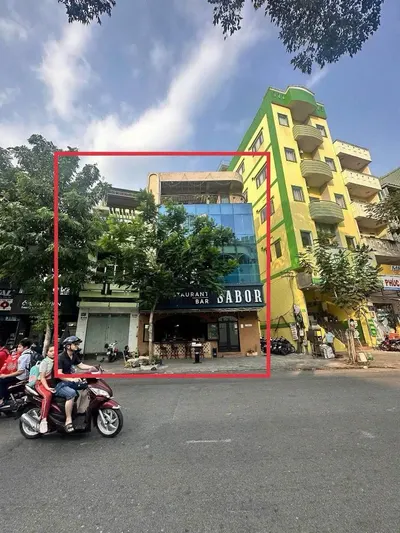
In the ever-volatile Ho Chi Minh City real estate market, securing assets that generate stable cashflow and possess capital appreciation potential is paramount for experienced investors. Today, we delve into an analysis of a prime commercial property for sale: the building at 22 Nguyen Binh Khiem, Tan Dinh Ward, District 1. With a price tag of 400 billion VND and a substantial floor area of 2098m², this is a deal worth dissecting.
1. Analysis of the Asset at 22 Nguyen Binh Khiem, District 1
Basic Information:
- Address: 22 Nguyen Binh Khiem, Tan Dinh Ward, District 1. A central location with easy connectivity to other bustling business districts.
- Land Area: 337.5m² (13m Width x 27m Length). A relatively square plot, conducive for functional planning.
- Asking Price: 400 billion VND. This equates to 1.1 billion VND/m² of land, a significant figure that demands superior returns to justify.
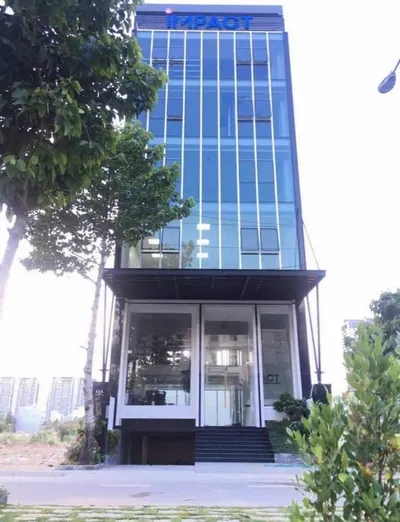
- Structure: 2 Basements + Mezzanine + 8 Floors. Total built-up floor area is 2098m². This configuration is suitable for office leasing or a boutique hotel model.
- Existing Lease Agreement (CF): 550 million VND/month. This is a major plus, indicating the asset already has a stable operational cashflow. This translates to an estimated annual revenue of approximately 6.6 billion VND.
- Legal Status: Private Pink Book (So Hong Rieng). Ensures transparent legal standing, facilitating transactions and bank financing.
Preliminary Assessment: The building is situated in District 1, the city's most valuable real estate area, consistently attracting major corporations and high demand for office and accommodation spaces. The large floor area, diverse structure, and existing lease agreement are positive factors. However, the 400 billion VND price tag necessitates a meticulous ROI calculation.
2. Comparison with Other Assets: Hoan My Eye Hospital (Dist. 3) & Phan Dang Luu Building (Dist. 3)
For a more objective perspective, we must contextualize the Nguyen Binh Khiem asset by comparing it with other major commercial properties on the market:
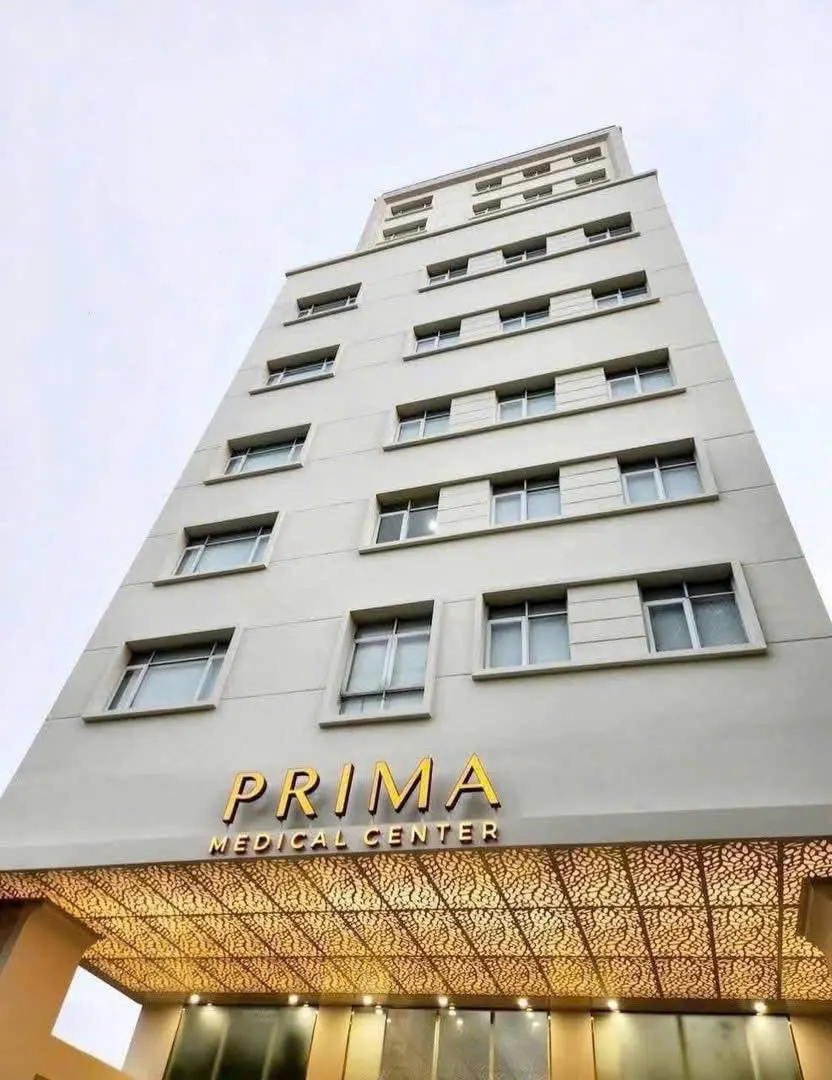
2.1. Hoan My Eye Hospital - Share Transfer at Ky Dong, District 3
- Address: 27–27A Ky Dong, Ward 9, District 3. An area with a high concentration of medical facilities and premium offices, also a prime location comparable to District 1.
- Land Area: 17m x 32m (583m²). A large, square land plot.
- Structure: 2 Basements + 12 Floors. Significantly larger scale than the Nguyen Binh Khiem building.
- Total Floor Area: 4,410m². Double the floor area of the Nguyen Binh Khiem property.
- Completion Year: 2019 (Modern construction, medical standards). A new asset requiring minimal initial repairs.
- Legal Status & Form: Medical land – private ownership. 100% share transfer. This form of transaction can be more complex than a direct asset sale.
- Transfer Price: 420 billion VND.
Comparative Analysis (Hoan My vs. Nguyen Binh Khiem):
- Price/m² Land: Nguyen Binh Khiem: 400B / 337.5m² ≈ 1.18B VND/m². Hoan My: 420B / 583m² ≈ 720 million VND/m². Clearly, the land price in Nguyen Binh Khiem is significantly higher.
- Price/m² Floor Area: Nguyen Binh Khiem: 400B / 2098m² ≈ 190 million VND/m². Hoan My: 420B / 4410m² ≈ 95 million VND/m². The Hoan My building offers an advantage in price per square meter of built floor area.
- Cashflow: Nguyen Binh Khiem has a lease agreement of 550 million VND/month (6.6 billion VND/year). Hoan My Hospital is a specialized, operational asset. Quantifying immediate cashflow without specific business operation data is difficult, but the potential for healthcare sector exploitation in the area is substantial.
- Scale & Potential: Hoan My has double the floor area, modern structure, and is a specialized asset. If the investor has a focus or experience in the medical field, this could be a more attractive option in terms of scale and operational potential adhering to standards. However, the share transfer mechanism requires thorough due diligence.
2.2. 24-Story Building on Phan Dang Luu Frontage, District 3
- Land Area: 25m x 40m, recognized as 968m² of land. A very large land area, ideal for large-scale projects.
- Total Construction Area: 13,500m². A colossal building compared to the other two assets.
- Structure: 4 Basements + 20 Floors. Scale comparable to a hotel or Grade A office building.
- Amenities: 3 elevators, fire protection, concealed air conditioning system. Fully equipped to Grade A office/hotel standards.
- Price: Over 1,000 billion VND (1.xxx billion).
Comparative Analysis (Phan Dang Luu vs. Nguyen Binh Khiem):
- Scale: The Phan Dang Luu building has significantly larger land and floor areas than Nguyen Binh Khiem.
- Price: The absolute value of the Phan Dang Luu building is 2.5 times higher, but price per m² of land and floor area needs more detailed calculation.
- Cashflow: No lease agreement information is provided. However, given its scale and location, the potential for office leasing or commercial service operations is immense, potentially generating billions of VND in monthly revenue.
- Investment: The Phan Dang Luu building is a massive asset, demanding enormous capital and a sophisticated operational strategy. It is suitable for large investment funds or investors with experience managing large-scale buildings.
3. ROI and Cashflow Analysis of the Nguyen Binh Khiem Building
With an asking price of 400 billion VND and current rental revenue of 550 million VND/month (6.6 billion VND/year), we can estimate the initial ROI as follows:
ROI = (Annual Revenue / Total Investment Value) * 100%
In this case, considering the sale price as the investment value:
ROI (before tax and operating expenses) = (6.6 billion / 400 billion) * 100% ≈ 1.65%/year.
This is a rather low ROI, especially when compared to current bank savings interest rates or other investment channels that can offer relatively safe returns of 5-7%/year. This suggests:
- Asset Appreciation Potential: The 400 billion VND price tag may already factor in the long-term capital appreciation of real estate in District 1. Investors acquiring this asset might be banking on future increases in land and building value rather than short-term rental income.
- Cashflow Optimization Potential: The 550 million VND/month lease agreement might be an old contract or not fully optimized. If lease terms can be renegotiated at a higher rate, or if the property's function can be converted to a more profitable model (e.g., Grade A office space, high-end boutique hotel), the cashflow could improve significantly.
- Operating Costs and Taxes: The above calculation does not include building operating expenses (maintenance, security, staff, utilities, etc.) and taxes (corporate income tax, non-agricultural land use tax...). These costs will reduce the net profit.
4. Forecasts and Risks
For the Nguyen Binh Khiem building:
- Pricing Risk: The land price of 1.1 billion VND/m² in District 1 is extremely high. If the real estate market enters a correction phase, the asset's value may not appreciate as expected, or could even decline.
- Cashflow Risk: The current lease agreement may not be renewed, or the tenant might face financial difficulties. Finding new tenants at the desired price point amidst competition could be challenging.
- Legal Risks: Although it has a private Pink Book, thorough due diligence on zoning, construction permits, and land use rights is mandatory.
- Appreciation Potential: District 1 consistently experiences stable long-term real estate value growth due to its unique location and perpetual high demand. If the investor has a long-term vision and sufficient financial capacity to wait, this could be a profitable investment in the future.
Compared to Hoan My Eye Hospital:
- Transaction Form Risk: Share transfers carry more risks than direct asset sales, requiring meticulous due diligence on the company's financial and legal standing.
- Industry Risk: If the investor lacks experience or connections in the medical field, operating the hospital could be difficult.
Compared to Phan Dang Luu Building:
- Capital Risk: Requires a massive initial capital outlay, posing risks if the market experiences significant volatility and finding suitable tenants for such a large scale proves difficult.
5. Conclusion and Investment Recommendation
From an investment perspective focused on cashflow and short-term ROI, the building at 22 Nguyen Binh Khiem, priced at 400 billion VND with an initial ROI of approximately 1.65% (before expenses), is not a particularly attractive option. This price seems to heavily weigh on long-term asset appreciation potential and future cashflow optimization capabilities.
Recommendations:
- For investors prioritizing cashflow: Thoroughly assess the potential to improve cashflow from the current lease agreement or through functional conversion. Without a clear plan to increase revenue, this asset may yield lower returns than anticipated.
- For long-term investors: If you believe in the long-term appreciation of real estate in District 1 and have the financial capacity to wait, this could be a strategic asset. However, carefully calculate the opportunity cost and compare it with other investments offering potentially better returns.
- Consider other options: The Hoan My Eye Hospital (Dist. 3) with its more attractive price per m² of floor area and specialized exploitation potential (if you have medical industry experience), or the Phan Dang Luu Building (Dist. 3) if you can mobilize significant capital and have a robust operational strategy, might be more compelling choices depending on your risk appetite and investment goals.
Before making a decision, detailed due diligence on the legal, financial, and operational potential of each asset is imperative.