Problem: Is the vacant building on Tran Hung Dao a worthwhile investment?
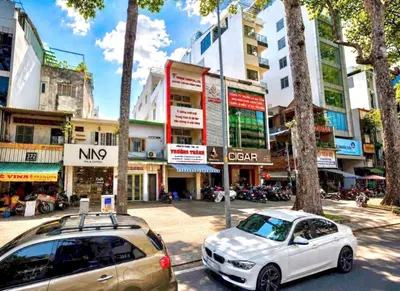
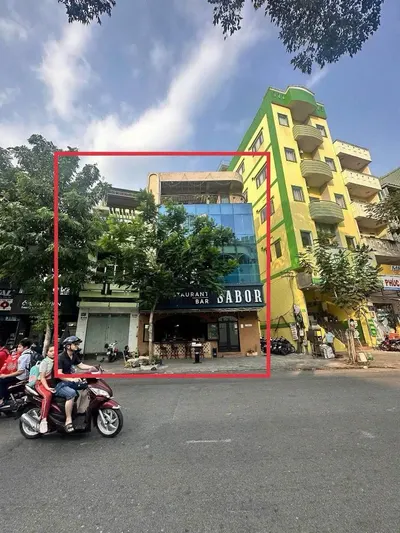
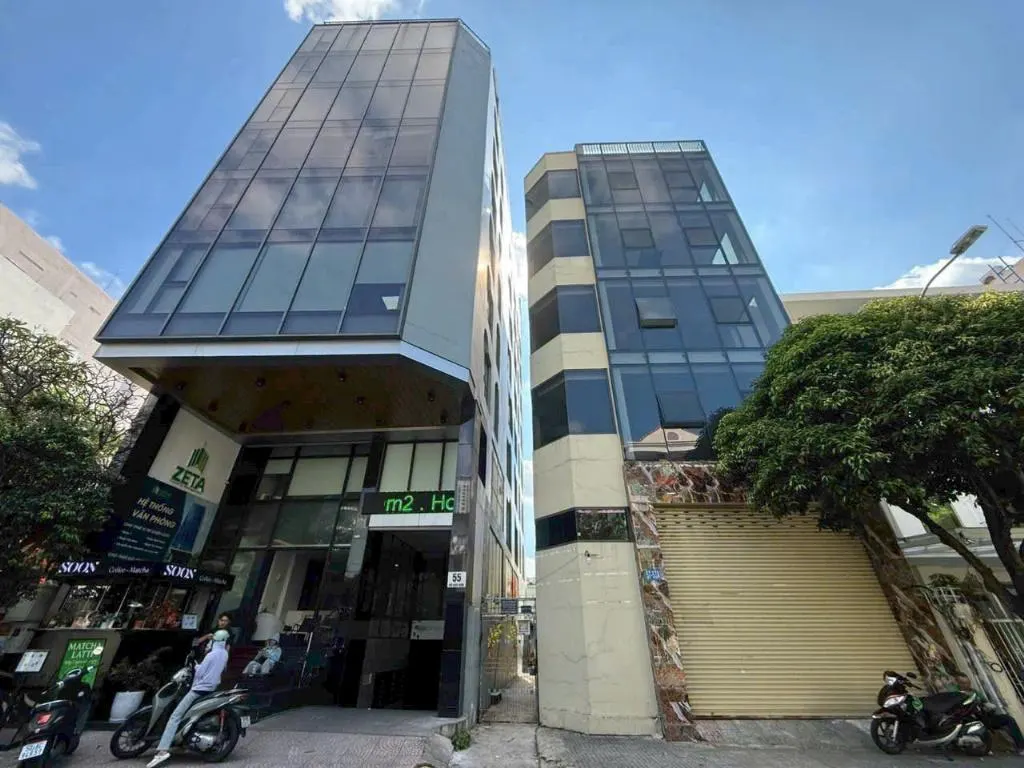
The real estate market in District 1 is always vibrant, but finding an asset with stable profitability is not easy. The 7-story building at 57-57A-55/2 Ho Hao Hon, Co Giang Ward, District 1 is being offered for sale at VND 115 billion. The question is: at this price, is this an attractive investment, especially since the building is vacant and ready for immediate exploitation?
Specific data about the building
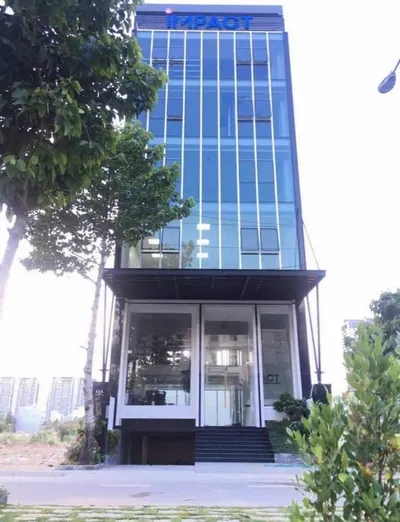
The building has a land area of 198.6m2 (7.9x25m), a construction area of 1007m2, and a structure of 1 basement and 7 floors. The location is right on Tran Hung Dao, only a 5-minute drive from Ben Thanh Market, an area with a high population density and bustling commercial activity. Currently, the building is vacant, allowing investors to customize and exploit it according to a suitable business model. The asking price is VND 115 billion, equivalent to about VND 579 million/m2 of construction. Compared to similar buildings in the area, this price seems competitive, but a more detailed analysis of exploitation potential and cash flow is needed.
Comparison with other investment options in the area
To assess the feasibility of this investment, we need to compare it with other options in the area. One is investing in serviced apartments (CHDV). With an area of 1007m2, it can be divided into about 10-15 rooms, with an average rental price of VND 20-30 million/month/room. Thus, rental income can reach VND 200-450 million/month, equivalent to VND 2.4-5.4 billion/year. However, operating costs (electricity, water, maintenance, management) can account for about 20-30% of revenue, reducing net profit to VND 1.68-3.78 billion/year. Two is renting out office space. With a 7-story structure, it can be rented out as a whole or divided into smaller offices. Office rental prices in District 1 range from VND 400,000 - 800,000/m2/month. If the entire building is rented out at VND 600,000/m2/month, revenue can reach VND 604.2 million/month, equivalent to VND 7.25 billion/year. Operating costs are similar to CHDV, about 20-30%, reducing net profit to VND 5.07-5.75 billion/year. Three is self-business. With a central location, the building can be used to operate businesses such as restaurants, hotels, or shopping centers. However, this form requires a larger capital investment and professional management experience.
Forecast & Risks
The forecast for the District 1 real estate market in the next 5 years may grow steadily, with an average growth rate of 5-10%/year. However, it is also important to note potential risks such as interest rate fluctuations, policy changes, and competition from new projects. If interest rates increase by 2%/year, borrowing costs will increase, reducing net profit. If policies change, it may affect the ability to exploit and the value of the asset. If new projects appear in the area, competition will increase, reducing rental prices and revenue.
Conclusion & Recommendation
At VND 115 billion, the building on Tran Hung Dao has attractive profit potential, especially if exploited effectively as an office or CHDV model. Estimated ROI can reach about 8.5%/year, higher than traditional investment channels such as savings deposits or bond investments. However, investors need to carefully consider potential risks and have a reasonable financial management plan. I recommend conducting a thorough legal and building condition assessment, and exploitation potential before making an investment decision. At the same time, it is necessary to have a contingency financial plan to deal with unexpected market fluctuations.