Investment Analysis: Prime CBD District 3 Grade A Building - 1200 Billion VND
As the Ho Chi Minh City real estate market continues to fluctuate, identifying assets with true value and sustainable profit potential remains a top priority for experienced investors. Commercial real estate, particularly Grade A office buildings in prime locations, consistently attracts attention due to their ability to generate stable cash flow. This analysis delves into a noteworthy investment opportunity: a Grade A building situated right in the heart of District 3, with an asking price of 1200 billion VND. We will comprehensively evaluate its scale, structure, legal status, and most importantly, its financial potential to determine if this is a worthwhile investment.
1. Specific Asset Data
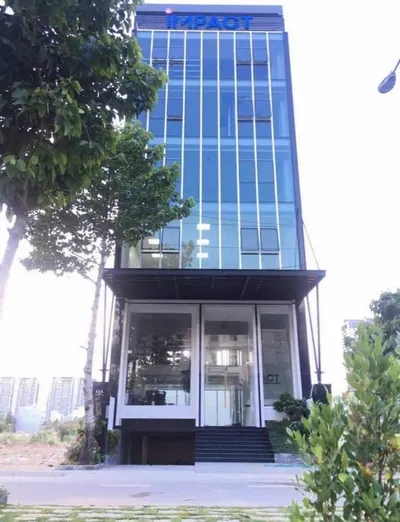
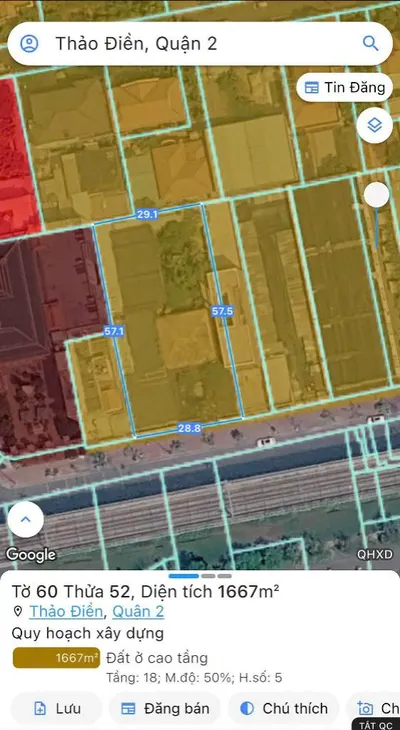
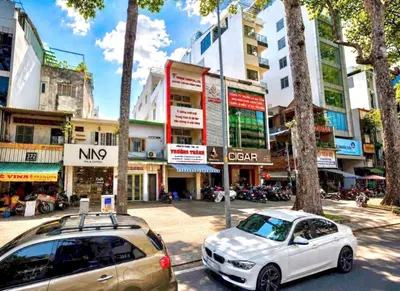
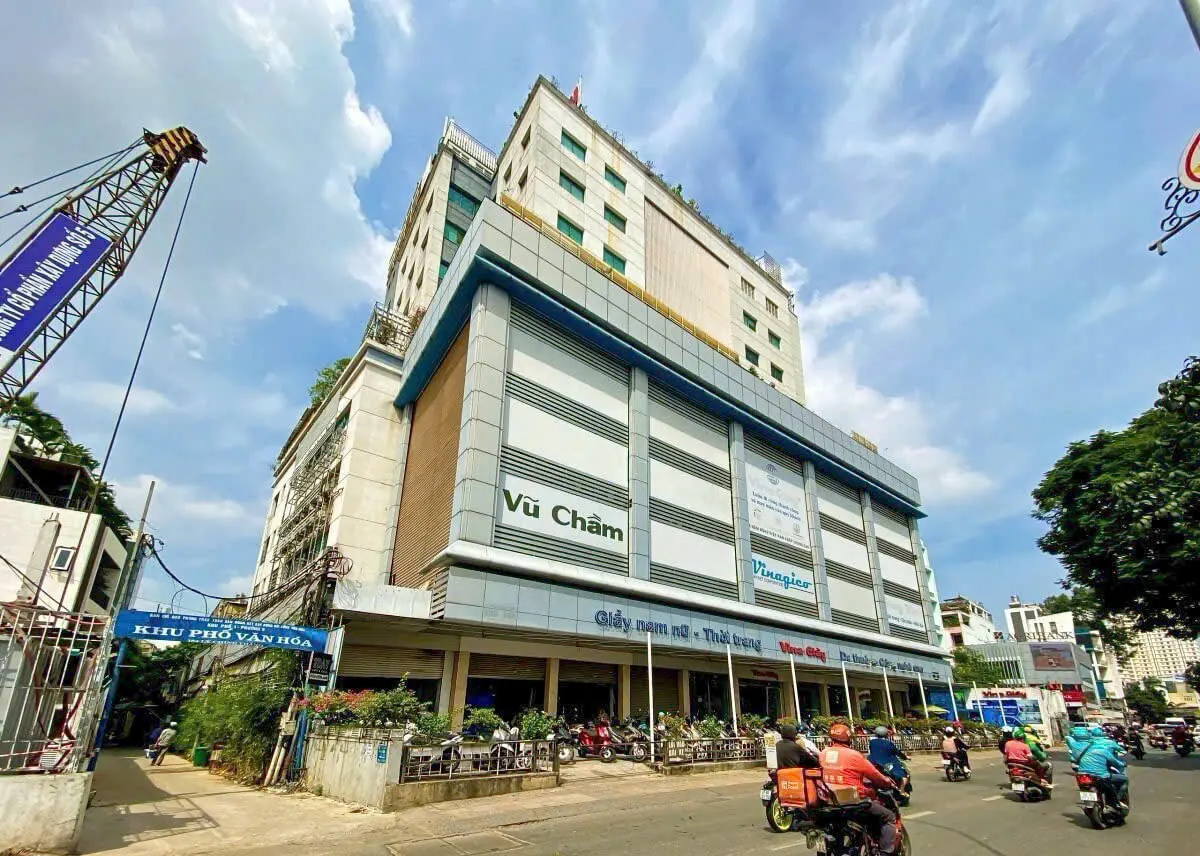
The initial information about this building provides an impressive overview. Located on a prime street in District 3, one of the city's most dynamic and valuable economic zones, the building boasts a strategic position, offering easy access to amenities and transportation links. The recognized land area is up to 1,500m2, with an impressive frontage of 47m x 38m, indicating an advantage in scale and optimal utilization potential. The total usable floor area reaches 7,000m2, spread across 1 basement level and 13 upper floors, along with 2 modern elevators, ensuring efficient operation for various business types, especially rental offices.
The building's structure includes a basement, a crucial element for optimizing space, usable for parking or storage. The 13 floors provide ample space suitable for rental offices, small retail centers, or other premium services. The presence of 2 elevators is a significant plus, reducing waiting times for occupants, particularly during peak hours, and enhancing tenant experience. The property's legal status is described as 'clean,' a key factor ensuring transaction security and transparency, minimizing potential legal risks for investors.
The asking price of 1200 billion VND places this building in the high-end real estate segment, requiring substantial investment capital. However, given its central location, large area, and modern structure, this price likely reflects its exploitation potential and commercial value. For an accurate assessment, we need to further analyze financial factors such as expected Return on Investment (ROI), monthly/annual cash flow, and future appreciation potential.
2. Cash Flow & ROI Analysis
For an experienced investor, the most critical factor when considering an office building is its ability to generate consistent cash flow and attractive returns. With a total floor area of 7,000m2, the rental potential is immense. Assuming the entire area can be leased as office space to businesses, Grade A office rental rates in central District 3 currently range from approximately 25-40 USD/m2/month (excluding VAT and management fees). Taking an average of 30 USD/m2/month, we can estimate the total monthly rental revenue:
Monthly Rental Revenue = 7,000 m2 * 30 USD/m2 = 210,000 USD/month.
Converting to VND at an exchange rate of 25,000 VND/USD, the estimated monthly revenue is: 210,000 * 25,000 = 5,250,000,000 VND.
Estimated annual rental revenue: 5,250,000,000 * 12 = 63,000,000,000 VND (approximately 63 billion VND).
However, this is gross revenue. We must deduct operating and management expenses. These costs include: personnel (management, security, cleaning), maintenance, electricity, water, common area internet, property taxes (if any), and other miscellaneous expenses. Assuming operating and management costs account for approximately 15-20% of gross revenue.
Using 18% for operating costs, we have:
Annual Operating Costs = 63,000,000,000 * 18% = 11,340,000,000 VND.
The estimated net profit from leasing activities (before corporate income tax and financing costs if debt is involved) is: 63,000,000,000 - 11,340,000,000 = 51,660,000,000 VND.
With an asking price of 1200 billion VND, the Gross Yield for this investment would be:
Gross Yield = (Annual Rental Revenue / Investment Value) * 100%
Gross Yield = (63,000,000,000 / 1,200,000,000,000) * 100% = 5.25%.
The Net Yield would be:
Net Yield = (Annual Net Profit / Investment Value) * 100%
Net Yield = (51,660,000,000 / 1,200,000,000,000) * 100% = 4.3%.
A Net Yield of 4.3% might be considered relatively low compared to the expectations of many real estate investors in Vietnam, especially when compared to other investment channels or higher-yielding real estate projects. However, the potential for asset appreciation and the prime location need further consideration.
3. Location Comparison & Evaluation
For an objective assessment, we need to compare this asset with equivalent investment options or other properties in the same area. Central District 3 is one of the areas with the highest commercial real estate values in Ho Chi Minh City. Grade A office buildings here consistently maintain high occupancy rates and stable rental prices. However, new supply in this area is very limited due to exhausted land reserves.
Compared to office buildings in District 1, this building might have slightly lower rental prices but offers advantages in terms of space (large frontage, extensive land area) and potentially less competitive pressure. Compared to areas outside the center, the 1200 billion VND price tag is a significant barrier, but it offers assurance of liquidity and long-term appreciation potential.
The 'clean legal status' is a major plus, providing investors with much greater peace of mind compared to dealing with complex legal issues that might arise. The 1,500m2 land area in a central location is extremely valuable and could offer superior exploitation potential in the future, such as redevelopment or expansion.
However, it's important to note that the 4.3% net yield is based on assumptions of 100% occupancy and average rental prices. In reality, achieving 100% occupancy for a large building like this may take time and require continuous marketing and sales efforts. Additionally, management costs can fluctuate.
4. Forecast & Risks
The Ho Chi Minh City real estate market, particularly the Grade A office segment in the CBD, is expected to grow steadily in the long term due to economic development and increasing demand for office space from domestic and international businesses. With limited supply, the value of well-located buildings like this is projected to continue increasing.
Assuming an asset value appreciation of 5-7% per year, the building's value could reach approximately 1,560 - 1,680 billion VND after 5 years. This offers the potential for compound returns, including rental income and capital appreciation.
However, there are risks to consider:
- Economic Volatility: Economic downturns can affect office space demand, leading to higher vacancy rates and downward pressure on rents.
- New Competition: Although new supply is limited, other premium office projects in the vicinity can still create competition.
- Rising Operating Costs: Electricity, water, and maintenance costs may increase over time, impacting net profit.
- Planning Changes: Despite clean legal status, future zoning changes could affect the building's exploitation potential.
- Liquidity Risk: With a price of 1200 billion VND, finding a subsequent buyer when needing to divest might take longer than for lower-value assets.
5. Conclusion & Recommendation
The Grade A building on a prime street in District 3, with an asking price of 1200 billion VND, represents an investment opportunity in high-value commercial real estate with a strategic location and transparent legal status. Although the current net yield (estimated at 4.3%) may not seem particularly attractive to some investors' expectations, the long-term asset appreciation potential and the scarcity of the location are significant compensating factors.
Recommendation: For investors with substantial capital, a long-term vision, and a preference for stability, legal security, and capital appreciation potential, this could be a worthwhile investment. However, investors should conduct more detailed due diligence on the current rental market, actual operating costs, and related legal aspects. If a better price can be negotiated or an effective exploitation strategy implemented to optimize rental revenue, the return on investment could be significantly improved. Thorough comparison with other commercial real estate investment options in the market is advised before making a final decision.