Investment Analysis: CHDV Building Tran Hung Dao, District 1 - A 200 Million VND/Month Cashflow Opportunity
In a dynamic real estate market, securing stable and sustainable cashflow investments is paramount for experienced investors. One attractive avenue is serviced apartment buildings (CHDV) in prime locations with consistent rental demand. Today, we delve into a potential asset: a CHDV building on the prominent Tran Hung Dao street, District 1.
1. The Challenge: Seeking Stable Cashflow from Central Real Estate
Ho Chi Minh City's real estate market, especially in central districts like District 1, always draws investor interest due to its appreciation potential and lucrative exploitation prospects. However, with significant capital, a strategy focused on consistent monthly cashflow, rather than solely relying on future price appreciation, is a prudent investment approach. The question is: Does this CHDV building truly meet expectations for cashflow and long-term investment returns? Is the asking price of 96 billion VND commensurate with its actual exploitation value and future growth potential?
2. Specific Asset Data Provided
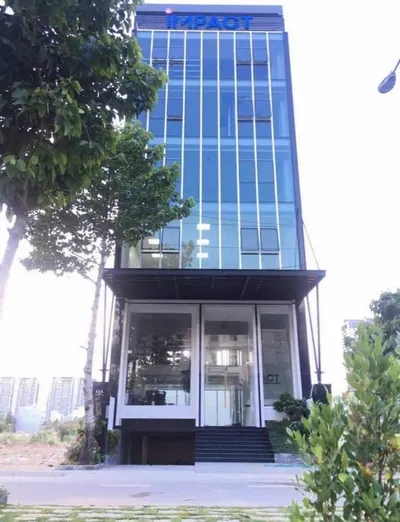
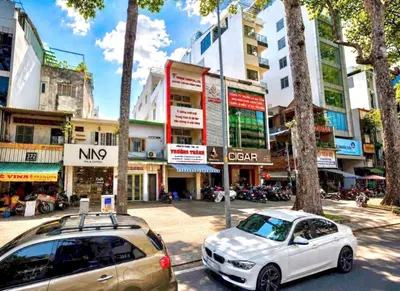
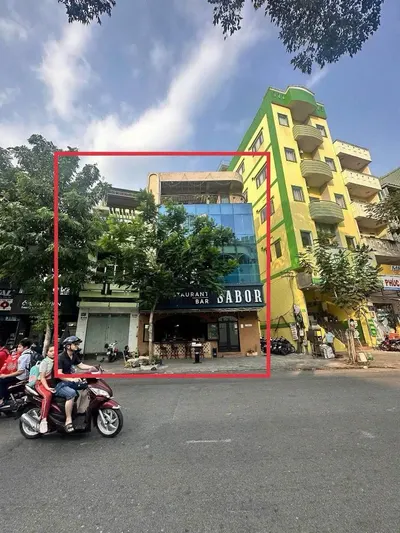
The asset in question is a CHDV building located on the main street of Tran Hung Dao, District 1. This is a major artery connecting key city areas, ensuring accessibility and attracting a diverse tenant base.
- Location: Tran Hung Dao street, District 1.
- Land Area: 12.5m x 21m. This provides a relatively wide frontage, beneficial for business and visibility.
- Recognized Area: 252m2. This indicates efficient land utilization.
- Structure: 1 basement + 6 floors. This maximizes usable space, including commercial and apartment areas.
- Number of Serviced Apartments: 17 units. A substantial number, allowing for diversified income from multiple tenants.
- Furnishings: Fully equipped with high-class interiors. Crucial for the serviced apartment segment, attracting long-term tenants willing to pay a premium.
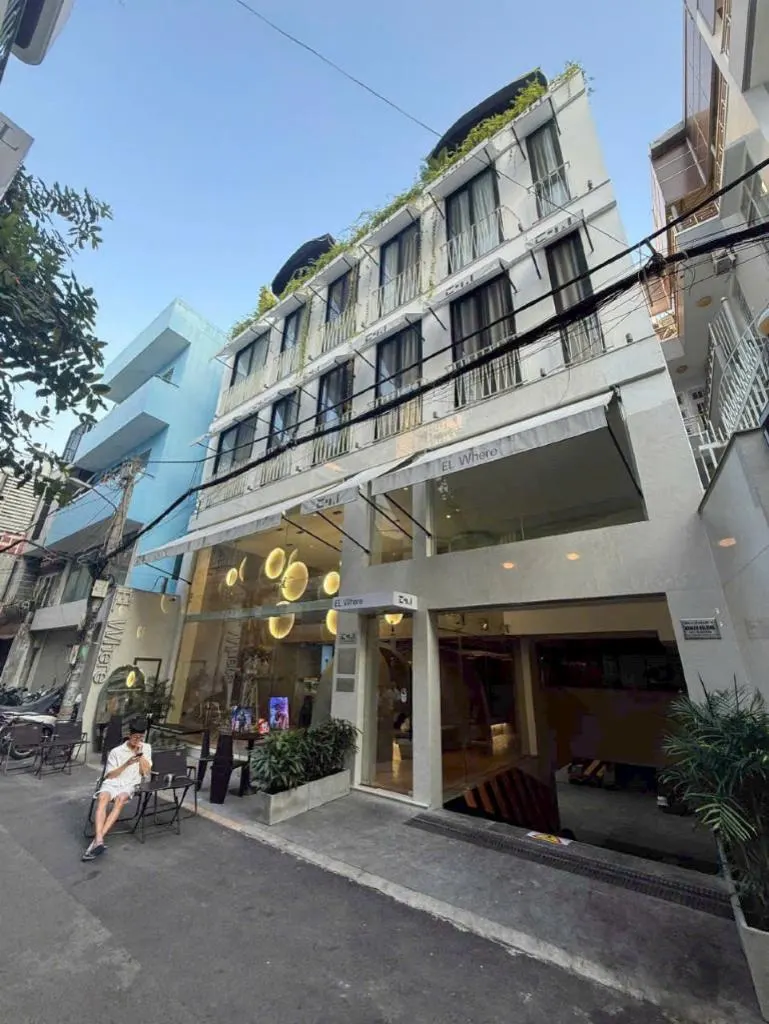
- Commercial Space: Lower 2 floors (ground & mezzanine) operating as a modern garden cafe. Combining accommodation with amenities like a cafe enhances resident convenience and creates supplementary income, boosting the building's overall appeal.
- Current Lease Contract: 200 million VND/month. This is the most critical figure for cashflow-focused investors, reflecting the building's current exploitation capacity.
- Asking Price: 96 billion VND (negotiable). This price requires careful evaluation based on exploitation efficiency, location, and growth potential.
- Contact: Tuờng Villa - 0934 161816.
3. Comparative Analysis & Investment Efficiency Assessment
To assess investment potential, we must contextualize the asset within the market and analyze key financial metrics.
3.1. Cashflow Analysis:
With a current lease income of 200 million VND/month, totaling 2.4 billion VND annually. The asking price is 96 billion VND.
Gross Rental Yield:
Gross Rental Yield = (Total Annual Rental Revenue / Asset Value) * 100%
Gross Rental Yield = (2.4 billion / 96 billion) * 100% = 2.5%.
A gross rental yield of 2.5% is modest, especially compared to other investment channels or higher-yielding rental properties. However, this is a gross figure. For a precise assessment, Net Rental Yield, after deducting operating expenses, maintenance, taxes, management fees, and loan interest (if any), is essential.
3.2. Operating Cost Analysis (Estimated):
Estimated expenses may include:
- Building Management Fees: Approximately 5-10% of rental revenue (120 - 240 million VND/year).
- Maintenance & Repair Costs: Around 1-2% of asset value annually (960 million - 1.92 billion VND/year). However, for CHDV buildings, costs can be higher due to usage frequency and equipment wear. An estimate of 5-10% of rental revenue (600 - 1.2 billion VND/year) might be more realistic.
- Utilities (common areas): Estimated at 100-200 million VND/year.
- Property/Land Use Tax (if applicable): Requires checking specific regulations.
- Personnel Costs (security, cleaning, reception): Estimated at 300-500 million VND/year.
- Marketing & Advertising Costs: Variable depending on market conditions.
Assuming total annual operating costs range from 1.5 to 2.5 billion VND.
Net Rental Yield:
Net Rental Yield = ((2.4 billion - Operating Costs) / 96 billion) * 100%
With operating costs at 2 billion VND/year: Net Rental Yield = ((2.4 billion - 2 billion) / 96 billion) * 100% = 0.41 billion / 96 billion * 100% ≈ 0.43%.
This figure indicates a very low net rental yield based solely on current rental income. This raises questions about whether the 96 billion VND asking price is overvalued relative to its actual exploitation potential, or if there are untapped revenue growth opportunities.
3.3. Location Analysis & Appreciation Potential
The Tran Hung Dao street frontage in District 1 is strategic, benefiting from:
- Convenient Transportation: Easy access to other central areas like District 3, District 5, Ben Thanh Market, and Phu My Hung financial district (via bridge).
- Bustling Commercial Area: Surrounded by offices, banks, shopping centers, restaurants, and hotels, attracting both business and leisure travelers.
- Infrastructure Development Potential: Future transportation and urban development plans could increase property values in the area.
However, it's important to note that property prices in District 1 are already very high. Appreciation rates might be slower compared to rapidly developing areas, but stability and security remain significant advantages.
3.4. Market Comparison
For an objective view, we need to compare the gross and net yields of this building with similar properties in District 1 or other high-rental-potential areas.
- CHDV buildings or small hotels in District 1: Typically have gross rental yields ranging from 3-6%, depending on size, quality, and occupancy rates.
- Commercial spaces for rent in District 1: Can offer higher gross yields, from 5-10% or more, but come with greater market risks and revenue volatility.
- Luxury apartments for resale: May appreciate faster but do not generate monthly cashflow.
With a gross rental yield of 2.5%, this building is below the average for income-generating rental properties. This could be due to:
- High Asking Price: 96 billion VND for a building with 252m2 land and 17 units is substantial.
- Suboptimal Revenue: Potential for rental increases or more units if restructured.
- Ineffective Cafe Business Model: Actual revenue from this segment needs thorough evaluation.
4. Forecasts & Risks
4.1. Cashflow Growth Forecast:
If the owner can increase average rents by 15-20% per unit (from ~14.1 million VND/month/unit to 16-17 million VND/month/unit), annual revenue could reach 2.7 - 2.9 billion VND. The gross rental yield would rise to approximately 2.8 - 3%. This is still modest but an improvement.
Alternatively, optimizing the garden cafe operations could significantly boost revenue. If the cafe contributes an additional 1-2 billion VND annually, total revenue could reach 3.4 - 4.4 billion VND/year, bringing the gross rental yield to about 3.5 - 4.6%.
4.2. Asset Appreciation Potential:
District 1's prime location guarantees long-term asset appreciation potential. However, the rate will depend on city planning, economic conditions, and surrounding development. A conservative 5-10% annual appreciation could see the asset value reach 127 - 160 billion VND in 5 years.
4.3. Risks to Consider:
- Rental Market Risks: Demand can fluctuate based on economic conditions, tourism, and competition from new CHDV projects.
- Operating Cost Risks: Maintenance, utilities, and personnel costs could exceed projections, reducing net yields.
- Legal Risks: Thoroughly vet legal documentation, zoning, and operational regulations for CHDV buildings.
- Management Risks: Managing a multi-unit building requires specialized expertise and experience.
- Pricing Risk: If the 96 billion VND asking price is too high for its income-generating capacity, achieving target ROI may be challenging.
5. Conclusion & Recommendation
The CHDV building on Tran Hung Dao street, District 1, boasts a prime location, long-term appreciation potential, and a stable 200 million VND/month rental income. However, with a current gross yield of only 2.5% and a projected very low net yield, it may not be an attractive deal if solely based on pure cashflow.
Recommendation:
Investors should carefully consider the following before deciding:
- Price Negotiation: Strive to negotiate the price down to a more realistic level reflecting its current exploitation capacity and growth potential. A price range of 60-70 billion VND might be more appropriate based solely on the 200 million VND/month cashflow.
- Optimization Plan: Develop a clear strategy to increase revenue from apartment rentals (rent hikes, service improvements) and the garden cafe. Detailed financial reports on the cafe's performance are essential.
- Deeper Cost Analysis: Request detailed operating cost breakdowns from the seller for recent years to calculate the most accurate Net Rental Yield.
- Comparative Analysis: Weigh this opportunity against other real estate investments (e.g., CHDV in other areas, rental houses, shophouses, or even financial instruments) to ensure the best ROI.
If the investor possesses the capability for restructuring, operational optimization, and has a long-term vision for area development, this could still be a worthwhile asset. However, at the current price, cashflow risks require significant attention.