Opportunity or Challenge? Investment Analysis of a 48 Billion VND Thao Dien House
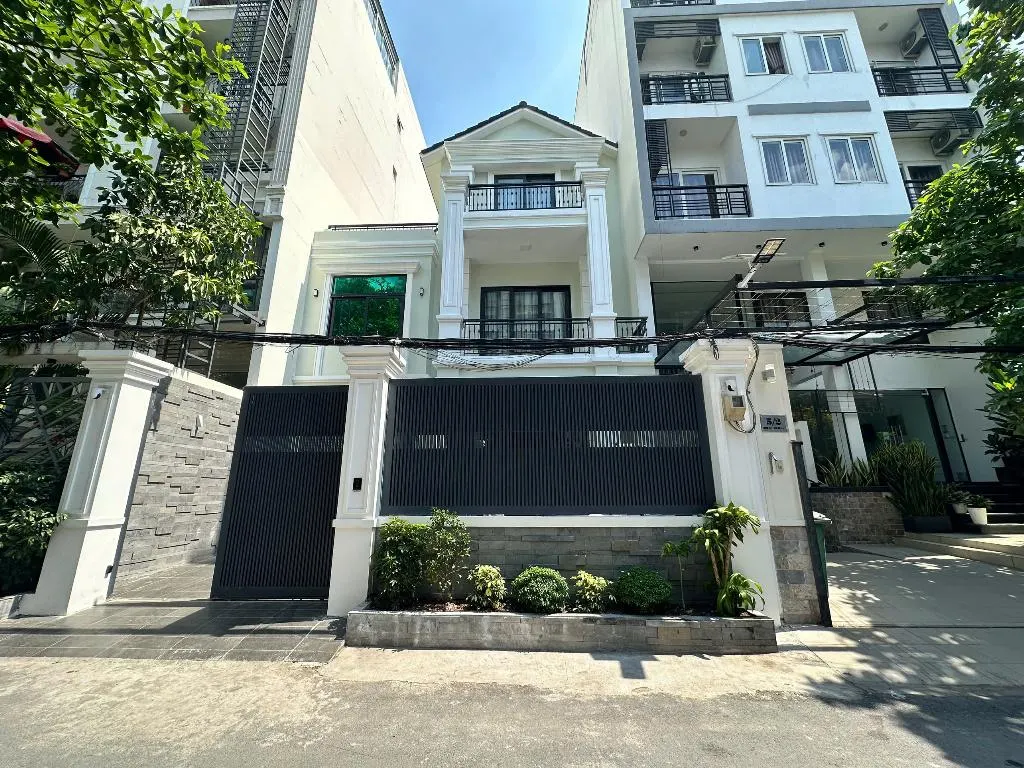
As an experienced investor, I always question the financial efficiency of every asset before committing capital. A house in Thao Dien, located at 5/4 Street 64, with a recognized area of 152m2 (dimensions 8.5x19m), featuring a ground floor and two upper floors (7 bedrooms, fully furnished), Southwest facing, with a pink book legal status, is being offered for sale at 48 billion VND. This is a substantial amount, especially given the current volatile real estate market. So, is this an attractive investment opportunity offering stable cash flow and high ROI, or merely an asset with nominal value awaiting the right conditions? This analysis will delve into the numbers and market trends to provide the most objective perspective for an investment decision.
Specific Property Data and Thao Dien Market Context
To accurately assess, we need to dissect each element of this asset. The house is situated at 5/4 Street 64, a relatively quiet road within the Thao Dien area. With a recognized area of 152m2 on an 8.5x19m plot, the selling price of 48 billion VND translates to approximately 315.7 million VND per square meter of land. This figure needs to be considered within the current Thao Dien market context.
Regarding structure, the house is solidly built with a ground floor and two upper floors, totaling three stories. A notable feature is its 7 bedrooms and full furnishings. The 7 bedrooms and complete furnishings are a significant advantage, especially if the investment goal is rental income. Tenants, particularly foreign families or small businesses looking for office/rental villas, often prioritize move-in ready homes that don't require additional renovation costs or furniture purchases. A Southwest orientation might be a minor drawback for some owner-occupiers due to afternoon sun, but for an investor focused on cash flow, this is not a decisive factor.
The pink book legal status is a major plus, ensuring transparency and security for the transaction. This minimizes legal risks and expedites the transfer process.
Thao Dien market context: Thao Dien has consistently been regarded as an upscale area, attracting an international expatriate community and Vietnamese high-net-worth individuals. Property values here are sustained by integrated infrastructure, diverse international amenities (international schools, hospitals, shopping centers, high-end restaurants), and a green, peaceful living environment. However, land prices on alleys and internal roads like Street 64 are typically lower than those on main arteries such as Xuan Thuy, Quoc Huong, or Nguyen Van Huong. Currently, land prices in car-accessible alleys in Thao Dien range from 280 million VND/m2 to 350 million VND/m2, depending on the specific location, alley width, and distance to main roads. At 315.7 million VND/m2, this house falls within the mid-to-upper range for the alley segment.
For rental potential, a 7-bedroom, fully furnished house in Thao Dien could generate an estimated rental income of 80 million to 120 million VND/month, depending on the actual quality of furnishings, specific alley location, and market conditions at the time of rental. Taking an average of 100 million VND/month, the gross rental yield would be (100 million x 12 months) / 48 billion = 2.5%. This figure is quite low compared to many investors' expectations for high cash flow, but it is common for high-value properties in prime locations where capital appreciation is the primary driver.
Specific Comparison: The 48 Billion VND House Versus Alternative Options
To make an informed investment decision, we need to compare this 48 billion VND house (referred to as Property A) with one or more potential alternative options in the same segment or area. For instance, an alternative (Property B) could be an empty land plot of a similar size (150m2) in Thao Dien at 300 million VND/m2 (totaling 45 billion VND) or an older villa of 150m2 at 40-42 billion VND requiring an additional 3-5 billion VND for renovation.
1. Initial Investment Value and Incidental Costs:
- Property A (48 billion VND): Fully completed, fully furnished, can generate cash flow immediately. Initial cost is 48 billion VND plus transfer taxes and fees. No significant construction or furnishing costs.
- Property B (Empty land 45 billion VND + construction): Lower initial land cost (45 billion VND). However, the investor will face construction costs (estimated 7-10 million VND/m2 of floor area for a similar house, with a total floor area of around 300-400m2, adding 2.1-4 billion VND) and furnishing costs (approximately 1.5-2 billion VND). The total final cost could reach 48.5 - 51 billion VND, not including construction waiting time and potential risks during construction.
- Property B (Older villa 40-42 billion VND + renovation): Lowest initial purchase price. Renovation costs of 3-5 billion VND could bring the total investment to 43-47 billion VND. However, unexpected costs during renovation of an older house are not insignificant and can inflate costs and extend timelines.
2. Cash Flow and Exploitation Potential:
- Property A: Generates immediate cash flow from rental, estimated at 80-120 million VND/month. Gross rental yield is approximately 2.5% (on the 48 billion VND price). This is an attractive factor for investors seeking stability.
- Property B (Empty land): No cash flow during the initial investment phase. Cash flow will only begin after construction and successful rental, taking at least 1-2 years.
- Property B (Older villa): Cash flow might be lower than Property A if not renovated, or interrupted during renovation. After renovation, cash flow could be similar to Property A, but the total investment capital might be slightly lower, leading to a higher rental yield.
3. Capital Appreciation Potential:
- Property A: As a completed house, capital appreciation primarily stems from the general growth of the Thao Dien market. The increase may be stable but unlikely to be as dramatic as with empty land.
- Property B (Empty land): Has higher capital appreciation potential if the market experiences boosts from urban planning, infrastructure, or scarcer land supply. Building a new, modern-designed house on empty land can also create significant added value.
- Property B (Older villa): Capital appreciation can come from buying at a good price and renovating for resale at a higher value.
4. Liquidity and Risks:
- Property A: At 48 billion VND, liquidity might be slower compared to properties under 30 billion VND. However, the segment of well-legalized, fully furnished houses/villas in Thao Dien still has its specific clientele.
- Property B (Empty land/Older villa): Liquidity for empty land is generally better if priced reasonably. Older villas after renovation can improve liquidity. Risks for Property A are mainly general market risks. Risks for Property B include construction risks, legal risks (for empty land without a construction permit), and unexpected cost risks.
Market Forecasts and Potential Risks
Based on the analysis, we can make some forecasts and risk assessments for this 48 billion VND investment in Thao Dien.
Forecasts:
- Value Stability: Thao Dien will continue to maintain its position as one of the most upscale residential areas in Ho Chi Minh City. Property values here, especially for the house/villa segment, are expected to grow steadily at 5-8% annually over the next 3-5 years, provided there are no major macroeconomic fluctuations. The completion of major infrastructure projects like Thu Thiem 2 bridge (completed), Thu Thiem 3 bridge (planned), expansion of Hanoi Highway, and Metro Line 1 Ben Thanh – Suoi Tien (soon to be operational) will further solidify the area's value.
- Sustainable Rental Demand: The demand for large, multi-bedroom, fully furnished houses/villas in Thao Dien will remain high, particularly from the expatriate community and high-income Vietnamese families. This ensures stable rental cash flow for Property A.
- High-end Segment Resilience: The high-end real estate segment, especially houses/villas in prime locations like Thao Dien, is generally less affected by market downturns than other segments. They tend to recover faster when the market stabilizes.
Potential Risks:
- Slow Liquidity: The 48 billion VND price point restricts this asset to a specific segment of buyers. In situations requiring quick liquidation, finding a suitable buyer might take longer.
- Low Cash Flow Yield: With a gross rental yield of only about 2.5%, if an investor relies on cash flow to service bank loans, financial pressure could be significant if interest rates rise. This is an investment where capital appreciation is expected to be the primary driver, not significant cash flow.
- Maintenance and Management Costs: A 7-bedroom, fully furnished house will incur higher maintenance and management costs to maintain quality and attract high-end tenants. Unexpected breakdowns of furnishings or appliances can occur.
- Supply Competition: Although Thao Dien has limited supply, if more new villa/townhouse projects are developed in nearby areas like An Phu or Thu Thiem at more competitive prices, it could affect the rental potential and valuation of the current property.
- Interest Rate Volatility: If lending interest rates continue to rise, the opportunity cost of holding cash or investing in other channels might become more attractive, reducing the appeal of real estate.
Conclusion and Investment Recommendation
The 48 billion VND house at 5/4 Street 64, Thao Dien, with an area of 152m2 and a 7-bedroom, fully furnished structure, is a valuable asset in one of Ho Chi Minh City's most expensive areas. The price of 315.7 million VND/m2 is reasonable for a car-accessible alley location in Thao Dien, especially considering it includes the value of construction and complete furnishings.
For investors seeking stable cash flow with low risk, this is a worthy consideration. With 7 bedrooms and full furnishings, the potential to generate rental income is clear and attractive to the high-end tenant segment. However, the gross rental yield of 2.5% indicates that capital appreciation is the primary expected driver for this investment, not dramatic cash flow.
If the goal is significant capital appreciation or optimizing profit per unit of capital, investors should consider other options like empty land for self-building or older villas requiring renovation, although these come with higher risks and longer waiting times. Before making a final decision, I recommend investors thoroughly assess the actual condition of the furnishings and structure, and consult recent transactions in the same area for a comprehensive and accurate perspective.